What is a Dividend Reinvestment Plan (DRIP)?





For the long-term investor, wealth creation is not just about buying at the right price; it also depends on what they do with the income generated from their assets. Dividends are one such source of income for long-term investors, and how they reinvest their dividend income to generate more returns for them often makes a huge difference in their long-term returns. This is where a Dividend Reinvestment Program or DRIP comes into play.
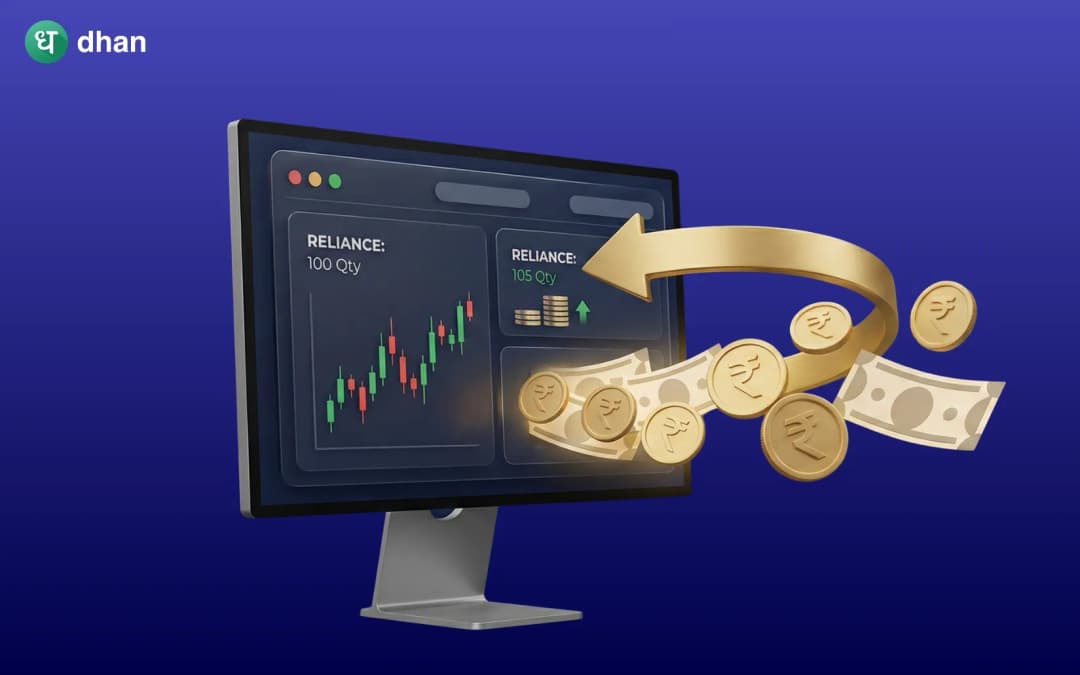
A Dividend Reinvestment Plan or DRIP allows dividend investors to reinvest the dividend into additional shares of the company, rather than taking the dividend in cash.
In this blog, we are going to talk about what a Dividend Reinvestment Program is, how it works, its advantages and disadvantages, and who should consider DRIPs.
Dividend Reinvestment Plan Meaning
A DRIP is a facility provided by a company, mutual fund, or investment platform whereby investors can reinvest their dividend income in the same security. This means that investors will not get any dividend payouts in their accounts; instead, they will buy more units or sometimes fractional units of the same share at a discount or at the prevailing market price.
Over time, this process helps investors capitalise on the power of compounding and assists them in steadily growing their wealth in the long term.
How does a Dividend Reinvestment Plan work?
The process of a Dividend Reinvestment Plan, or DRIP, can be broken down into a few easy steps, such as:
Step 1: An investor buys stocks of a company that has a DRIP program either directly or through a brokerage account.
Step 2: The company declares a dividend, which is a portion of the company's profits distributed to the shareholders on a predetermined schedule (e.g., quarterly, semi-annually, or annually).
Step 3: The dividend amount received is reinvested in buying new shares at the current market price or at a discount price, depending upon the DRIP terms. Some DRIPs involve a discount on buying new shares.
Step 4: The new shares are added to the investor's current holdings, increasing the investor's ownership in the company.
Step 5: This process is repeated with each subsequent dividend payment, allowing the investor to reinvest while taking advantage of compounding and accumulating more shares over a long period.
The terms and conditions of a DRIP vary from company to company; therefore, before selecting a DRIP program, investors should thoroughly review the terms and conditions of the DRIP program.
For example, let's assume that an investor has an existing holding of 500 shares of a company and the current trading price of that company's stock is Rs. 100 per share. Further, the company declares a semi-annual dividend of Rs. 1 per share with a DRIP program having a 5% discount on the share price for reinvested dividends.
If the investor chooses to reinvest in the DRIP program instead of receiving cash of Rs 500 (500 shares * Rs 1 dividend). The dividend amount received from this would buy more shares of the company at a discounted price.
At the current stock price of Rs. 100 per share, the discounted price for reinvestment buying would be Rs. 95 (Rs. 100 - 5% discount). Thus, the dividend amount of Rs. 500 will be used to buy 5.26 additional shares of the same company.
500÷95 = 5.26
After reinvestment of the dividend, the investor would hold 505.26 shares of the company against their earlier holding of 500 shares. This process would repeat after every subsequent dividend payment, which would gradually increase the investor's ownership stake in the company while capitalising on the power of compounding returns.
Benefits of Dividend Reinvestment Plan
Dividend Reinvestment Program on Dhan offer several compelling advantages to investors looking to optimise their portfolios and build long-term wealth. Some of those advantages are:
Compounding growth
The primary benefit of the Dividend Reinvestment Program is the power of compounding. Through steady reinvestment of dividends, investors can substantially accelerate the growth of their investment over time, whereby not only the principal capital but also the accumulating dividends earn further returns.
Dollar-cost averaging
DRIPs inherently provide Rupee-cost averaging. Because the dividends are invested on a regular schedule, often quarterly, shares are bought at different prices at various points in time. This strategy aids in reducing the chances of investing a large sum of money at a single high price because the cost of buying a share is averaged over a long period of time.
Reduced transaction Costs
Many company-sponsored DRIPs offer commission-free reinvestment of dividends. This can save a significant sum of money over the long term, particularly for investors who would have to pay a brokerage fee every time they bought more shares.
Automated investing
Many DRIPs automate the reinvestment of dividends without intervention from the investor. A "set it and forget it" plan that provides regularity for investment against market ups and downs, which often result in no need for an investor to remember to reinvest their cash dividends.
Accumulation of fractional shares
Fractional shares can be accumulated via DRIPs. This means that the entire amount of the dividend payment gets put to work rather than just having some amount of dividend cash not used, which is not large enough to buy a whole share. This maximises the reinvestment efficiency.
Long-term focus
By their design, DRIPs foster a long-term investment philosophy. They are most beneficial if they are allowed to operate for long periods of time, so that the compounding effect can actually kick in. Therefore, DRIPs are well compatible with retirement plans and other long-term financial objectives.
Drawbacks of DRIPs
While DRIPs offer several benefits, they also have some drawbacks, such as:
Tax implications
Dividends, even if reinvested, are considered taxable income in the year in which they are received. In other words, investors will have to pay taxes on the dividends that they never received.
Lack of control over purchase price
In an automated DRIP, investors do not have the choice of determining the exact price at which additional shares will be purchased.
Limited company selection (Direct DRIPs)
Direct DRIPs are not offered by all companies. If a company does not offer a direct DRIP, then investors may have to enroll through a brokerage firm. Those DRIPs may or may not offer commission-free reinvestment.
Complexity for active traders
The DRIPs are challenging to administer for active traders who regularly sell and buy stocks, because of the added recordkeeping of dividends reinvested and their corresponding adjusted cost basis for numerous small purchases.
Who should consider a DRIP?
DRIPs are well-suited for the specific types of investors, such as:
- Long-Term Investors: Individuals who have a long-term investment horizon, like saving for retirement or their child's education, will be the biggest beneficiaries of the compounding effect after a couple of years.
- Growth-Oriented Investors: Although frequently linked to income investing, DRIPs can be an effective tool for growth investors who want to maximise their accumulation of shares in high-quality, dividend-paying companies.
- Passive Investors: Those who prefer a hands-off approach to investing will appreciate the DRIPs, as their dividends have been put to work for them consistently, without them having to conduct all the market research again and again at each dividend payout.
- New investors: DRIPs are an attractive way to get started for investors who are new to the investing world. DRIPs are an accessible and cost-effective means of building wealth over the long term.
Summing It up!
A Dividend Reinvestment Plan (DRIP) turns dividends (passive income) into a compounding growth machine. An investor's dividends get reinvested, thus growing their holdings over time, availing the benefits of rupee cost averaging and compounding power to build wealth.
While DRIPs have some drawbacks, like taxation and overconcentration in a single stock, their advantages far outweigh the limitations for long-term investors.
Frequently asked questions (FAQs)
Which is better for long-term investors, DRIPs or taking cash dividends?
A dividend reinvestment plan is more suitable for investors who are interested in long-term wealth generation. It enables investors to increase their holdings of shares through reinvesting dividends, thus benefiting from compounding returns over a long period. On the other hand, cash dividends are more appropriate for investors like retirees who need regular income.
If dividends are reinvested through a DRIP, are they considered for taxation?
The answer is a 'yes', as dividends are liable to taxation, even if the dividends are reinvested instead of being received as cash. Investors then have to pay the tax on dividend income, depending on their relevant tax slab. Therefore, this is an important factor for investors to consider when they are availing the dividend reinvestment plan.
Can I stop or make changes in my dividend reinvestment program anytime?
Yes, most dividend reinvestment plans offer investors flexibility. An investor could initiate or stop dividend reinvestment plans when they want, according to their evolving financial goals.
Do dividend reinvestment plans offer fractional share purchases?
Yes, one of the key features of the dividend reinvestment plans is that they allow the buying of fractional shares. This ensures that the whole dividend amount is reinvested, even if it is not enough at the current market price to buy a whole share.
Who should avoid dividend reinvestment plans?
Dividend reinvestment plans are not suitable for those investors who only rely on dividend income to meet their daily expenses or require regular cash flow. This plan is also not suitable for investors who would want to achieve diversification with their dividend earnings rather than investing the dividend income in the same security.