Are you overpaying for Gold?



In the year 2026, owing to geopolitical conflicts and the uncertainty in the global economy, gold rates reached all-time highs in early 2026. While the underlying fundamentals for gold metal remain strong, the way most Indians purchase it in the form of physical gold is flawed.
While buying gold from a jewellery store, one needs to understand that they are not only paying for the precious metal; instead, they are also paying numerous hidden costs associated with it.
Therefore, when investors think about gold as an asset class, they should ask themselves one question: Are they really overpaying for their gold investment? In this blog, we will explore this question in detail.
What happens when investors buy gold from a showroom?
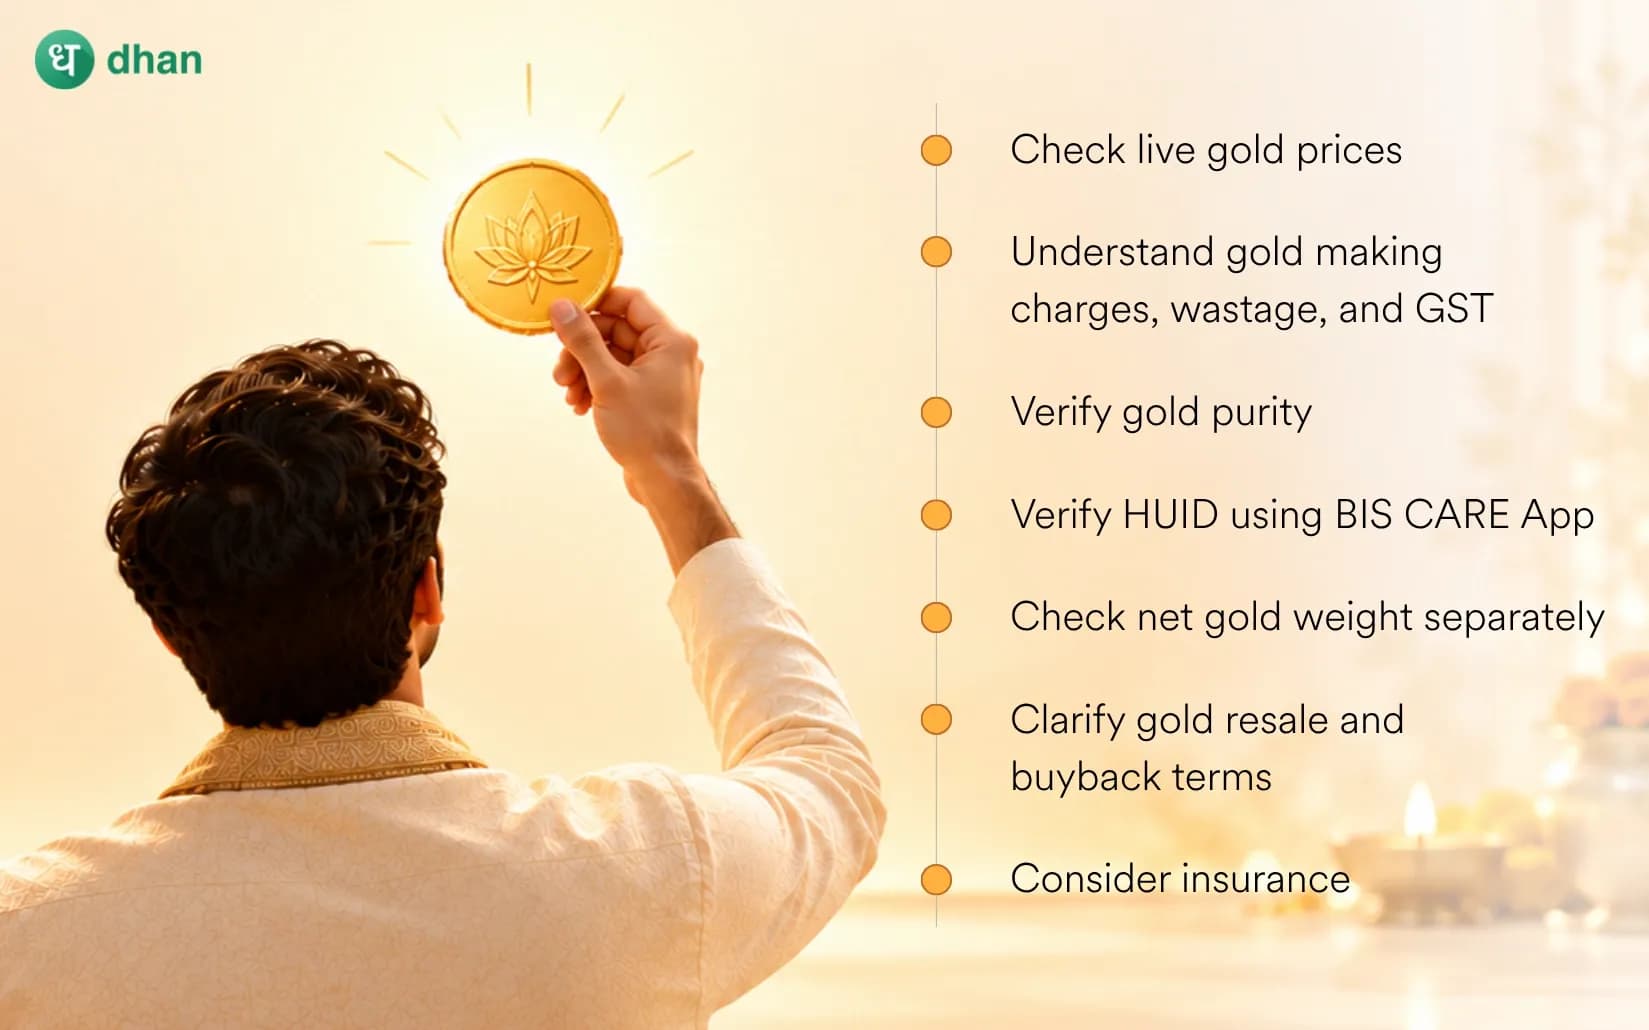
In order to get an idea about why investors tend to pay an extra amount while investing in physical gold, it is necessary for us to first analyse the final amount paid for the physical gold purchase. The baseline is the spot price, which is benchmarked daily by the India Bullion and Jewellers Association (IBJA); however, investors do not only pay gold spot prices for their investments.
First, there are making charges which include the costs incurred for making gold jewellery. Making charges usually account for 5%-25% of gold values, depending on the complexity of designs, resulting in up to a quarter of investor money going into making charges of the jewellery.
After that comes GST, which includes 3% GST on the total gold value and 5% GST on making charges. Lastly, BIS-certified centres charge hallmarking fees of about Rs. 45 per article plus GST.
Also, when these investors resell their physical gold to a jeweller even after the first day, the jeweller will be paying them according to the weight and purity of gold, and not according to the amount they paid for buying the gold, which results in 10% to 15% loss on the first day.
Smarter alternatives to avoid overpaying
If wealth creation is an investor's primary goal, then India's modern financial ecosystem offers various efficient alternatives to physical gold, which include.
Sovereign Gold Bonds (SGBs)
SGBs represent government bonds, which are denominated in grams of gold. SGBs act as substitutes for owning physical gold. SGBs are issued by the Reserve Bank of India on behalf of the Government of India, and are linked to the simple average price of 999 purity gold with zero making charges and zero storage cost.
Additionally, the RBI pays a fixed interest of 2.5% per annum on the face value of gold to investors, which is credited semi-annually, but SGBs come with a lock-in period of 8 years, while the early encashment/redemption of the bond is allowed after the fifth year. Thus, investors also get additional income from their investment along with the gold price appreciation.
Gold ETFs and Gold Mutual Funds
If investors want high liquidity without lock-in periods, Gold Exchange Traded Funds listed on NSE and BSE offer a compelling alternative as they track domestic physical gold prices. They represent physical gold in dematerialised form under SEBI's regulatory framework, where the physical gold is stored in secure vaults. Gold ETFs enable investors to purchase fractional units and bear no making charges, though fund expenses apply.
Gold mutual funds invest in gold-related assets, primarily gold ETFs. It offers a convenient way to gain exposure to gold without storage, security, or purity concerns, and also allows SIP investment.
Digital Gold
Digital gold is offered by authorised platforms. Digital gold allows investment from as little as ₹1. Although a 3% GST is charged, there are no making charges and the gold is kept in vaults of the providers, which can be redeemed in cash or physical gold at any time.
Although digital gold is still not regulated under the SEBI framework, this increases the risk associated with digital gold investments.
The bottom line
Gold is an alluring asset in terms of portfolio diversification and long-term wealth preservation. But how investors hold it is as important as the choice to hold it. It is less efficient to hold on to physical gold jewellery as an investment, as investors lose 10% to 15% the moment they walk out of the jewellery showroom.
By shifting towards gold ETFs, gold mutual funds, SGBs, and digital gold, investors can eliminate the exorbitant making fees, storage concerns, and ensure that every penny they invest is put to work creating wealth instead of paying for additional expenses. Thus, investors who want to avoid overpaying for their gold investments should invest in the above-mentioned modern financial instruments.