Debt mutual fund explained






When you talk about investing, you think about equity, growth, and high returns. Equities do play a vital role in creating wealth. However, not every financial goal should be based on high risk or volatility. You may have other goals like building an emergency fund, protecting your capital, or having a fund for short-term needs. In these cases, investors must prioritise stability over aggressive returns.
This is where debt funds should be a part of your portfolio. These funds offer predictable returns and carry relatively lower risk compared to equity funds. However, many investors tend to overlook debt funds or fail to understand how they work.
In this blog, we have explained what a debt fund is and how it works. You will also get to know the different types of debt funds. With detailed knowledge, you can integrate them into your disciplined investment strategy.
What is a debt mutual fund?
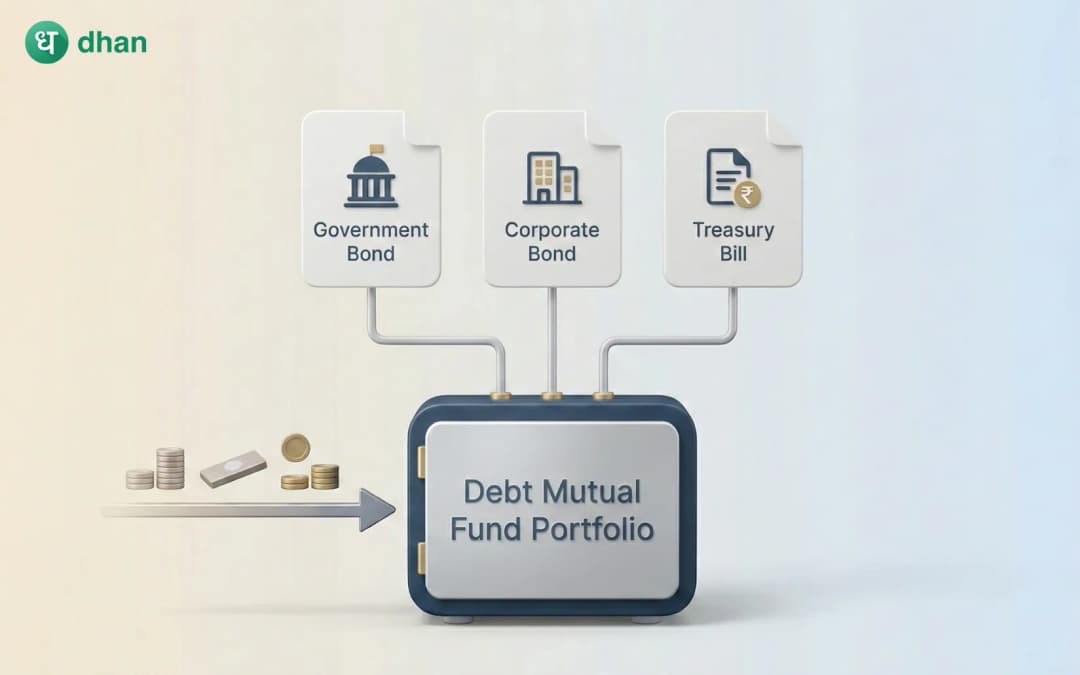
A debt mutual fund invests in fixed-income instruments. These may include:
- Bonds
- Treasury bills
- Commercial papers
- Certificates of deposit
- Other debt securities
From these instruments, you can enjoy interests at regular intervals. Interest is the primary source of returns for the fund.
Debt funds are different from equity funds since they don’t prioritise aggressive capital growth. Their goal is to preserve your capital while generating a steady income. The type of debt instrument that the fund invests in determines the level of risk and return.
Types of Debt mutual funds :
- Short-term or long-term Debt Mutual funds
- Government-backed or corporate Debt Mutual funds
- High-rated or lower-rated Debt Mutual funds
If you’re a conservative investor or want to avoid volatility, debt funds are for you. These funds are suitable for parking your money for short to medium durations, and they offer predictable returns. Although they are not as risky as equity funds, they are still linked to the market and are subject to certain risks.
How does a debt mutual fund work?
A debt mutual fund pools money from multiple investors. Then, the fund managers invest them in a basket of fixed-income securities. These securities pay interest, which ultimately contributes to the overall return of the fund. If there is any change in the market value of these securities, it affects the NAV of the fund.
The performance of a debt fund depends on two key factors.
Interest rate movement
With a drop in interest rates, existing bonds with higher interest rates gain value. This increases the NAV of the fund.
Again, when interest rates rise, the prices of bonds fall. As a result, your returns may temporarily be affected.
Credit quality
Debt funds invest in securities issued by governments, public sector entities, or private companies. Issuers with a high rating carry lower risk. On the contrary, the lower-rated ones offer higher returns, but they also carry a higher credit risk.
Types of debt mutual funds
Investors can choose from different types of debt mutual funds depending on the composition of their portfolio and duration.
Liquid funds
Liquid funds invest in very short-term instruments. The maturity period is up to 91 days. Primarily, these include treasury bills and high-quality money market instruments.
Investors use liquid funds to park extra cash for short periods. Along with high liquidity, these funds involve low risk and offer stable returns. So, they are a popular avenue for emergency funds or short-term parking of capital.
Ultra short and low duration funds
These funds invest in instruments with slightly longer maturities compared to liquid funds. Their goal is to deliver marginally higher returns, but at the same time, maintain relatively low risk. Investors consider ultra-short and low-duration funds for short-term goals, which range from a few months to about a year. Typically, these funds deliver better returns than savings accounts.
Corporate bond funds
Primarily, corporate bond funds invest in high-rated corporate bonds. With these debt mutual funds, you enjoy both safety and returns. Fund managers choose issuers with strong credit profiles. Corporate bond funds generally deliver better returns compared to government securities. However, they also carry moderate credit risk. Conservative investors looking for steady income with controlled risk often invest in corporate bond funds.
Banking and PSU debt funds
These funds invest mainly in debt instruments that are issued by:
- Banks
- Public sector undertakings
- Government-backed entities
These issues are well-regulated and financially strong. This implies the credit risk is relatively low. Investors looking for stability with slightly higher returns compared to liquid funds often invest in banking and PSU debt funds.
Gilt funds
If you’re conservative with your approach to investment and want to invest exclusively in government securities, go for gilt funds. They don’t carry any credit risk since the government itself issues the funds. However, gilt funds are sensitive to changes in interest rates. They perform well when the rates fall, and may fluctuate as the rates rise. Those with a long-term view on interest rate cycles often invest in these debt funds.
Dynamic bond funds
Fund managers of dynamic bond funds actively adjust the portfolio maturity based on expectations of interest rates. With this flexibility, investors can avoid timing the interest rate cycles themselves. If you want professional fund management across changing rate environments, dynamic bond funds may suit you.
Credit risk funds
Credit risk funds invest in lower-rated debt instruments so that they can generate higher returns. They carry an attractive return potential, but also come with a higher default risk. Experienced investors with a higher risk tolerance and a long investment horizon may find credit risk funds suitable for them.
Why investors use debt mutual funds
Debt mutual funds should be a part of your portfolio for several reasons.
Stability
When equity markets turn volatile, debt mutual funds serve as a cushion. They reduce fluctuations in your portfolio, thereby stabilising it.
Generating income
Retirees and conservative investors often want their returns to be predictable. Debt funds help them generate this income. If you have short and medium-term financial goals, debt funds are more suitable than equities, particularly when the timing risk is higher.
Diversification
Diversification is another key benefit of debt funds. Investors who combine equity and debt funds can reduce the overall risk of the portfolio and improve consistency in the long term. Debt funds can also help you park money temporarily as you wait for better opportunities.
Greater flexibility
Debt funds offer more flexibility compared to traditional fixed deposits. They also provide greater liquidity and come with the potential for more tax-efficient returns. Disciplined investors benefit from the stabilising effect of debt funds while creating long-term wealth.
Wrapping up
If you’re conservative with your approach to your investment or want to anchor your portfolio, debt funds are an excellent choice. The returns are predictable, and you can diversify your portfolio. It makes sense to balance your equity holdings with adequate debt instruments.
In the long run, consistent returns matter more than aggressive growth. With debt funds, you can achieve your financial goals with confidence.
FAQs on Debt mutual funds
Can debt mutual funds give negative returns?
Yes. Debt funds can deliver negative returns in the short term due to changes in interest rates or credit events.
Are debt funds safe during market crashes?
Compared to equities, debt funds offer more stability when markets crash. However, you must consider the credit quality and your investment horizon while assessing risk.
How long should I stay invested in debt funds?
Consider your investment goals when you choose a debt fund. For immediate goals, choose short-term debt funds. Long-term debt funds are suitable for longer horizons.
Can debt funds replace emergency funds?
Often, investors build their emergency funds through debt instruments. They carry low risk and offer liquidity, which makes them suitable for emergencies.
Do debt funds provide regular income?
Yes. Debt funds generate regular income through interest. However, the fund structure determines the payouts. For regular cash flow, you may also use SWPs in debt funds.