What is Liquid Fund?




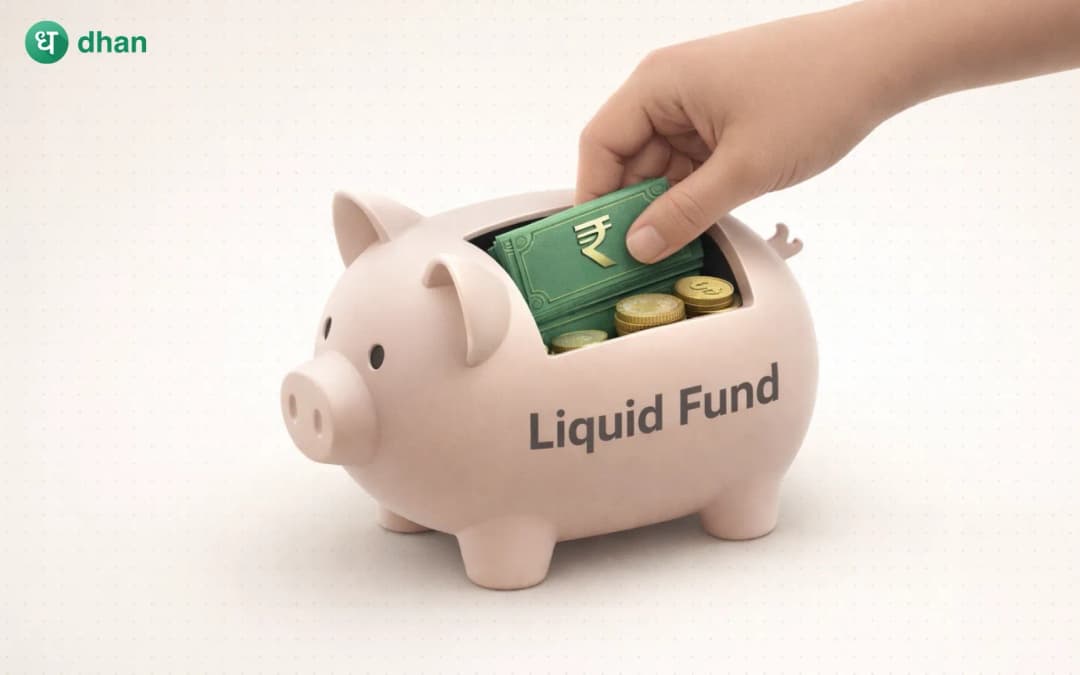


A liquid fund is one of the safest options to keep your excess cash in place temporarily without incurring too much risk. In this article, we are going to discuss what is liquid fund, its working process, its main characteristics, advantages, risks, and who should consider investing in them.
Liquid Fund Explained
A liquid fund is a category of debt mutual fund that invests primarily in highly liquid, short-term money market instruments and debt securities with very short maturities, usually not exceeding 91 days.
These instruments include:
- Treasury bills (T-bills)
- Commercial paper (CP)
- Certificates of deposit (CD)
The point of a liquid fund is to ensure your capital is secure and yet your money is readily available when you need it, usually in a single business day of redemption.
Liquid funds are governed by the Securities and Exchange Board of India (SEBI), which regulates the structure of liquid funds, their liquidity requirement, and investments allowed.
How do liquid funds work?
Now that you know what is liquid fund, let’s see how it works. By investing in a liquid fund, your money is pooled with that of other investors and invested in debt instruments.
The following is a simplified explanation of the working of a liquid fund:
Investment: You make an investment in a liquid fund, and your money is combined with that of other investors.
Portfolio construction: This money is invested by the fund manager in short-term investments like treasury bills, commercial paper and certificates of deposit.
Return generation: The primary source of return is through interest gained on such instruments. They can be seen in the Net Asset Value (NAV) of the fund.
Redemption: When you redeem your units, the fund sells these securities and credits your redemption amount, typically within one business day (T+1).
Since they invest in short-maturity instruments, the funds tend to be less sensitive to changes in interest rates than other debt funds, which assists in keeping the NAV stable.
Key features of liquid funds
The liquid funds possess a number of significant features that distinguish them from other types of investment options:
High liquidity
Liquid funds are created in order to provide instant access to your money in case of an emergency. In the majority of cases, the redemption proceeds are deposited in your bank account within a business day after you have made a withdrawal request.
Low risk
Liquid funds have a lower credit and interest rate risk in comparison with other mutual funds because they invest in the high quality short-term investments.
No lock-in period
There is no lock-in period with liquid funds, unlike fixed deposits or some other investment instruments. You are able to redeem your investment at any time with little or no exit load.
Stable returns
Liquid funds have relatively low returns, which are usually stable due to low volatility and investment in short-term instruments.
Low cost
The expense ratios of liquid funds are generally lower than the ratios of actively managed debt or equity funds. This can save you a higher percentage of returns.
Benefits of investing in liquid funds
Liquid funds offer several advantages for certain types of investors:
Capital preservation
Liquid funds are for safeguarding the principal amount, and this makes them appropriate for conservative investors or individuals who wish to avoid market fluctuations.
Better returns than savings accounts
The liquid funds tend to offer better returns as compared to the standard savings accounts, owing to the fact that they are exposed to market-linked short-term debt instruments.
Ideal for an emergency fund
Since liquid funds are highly liquid, they are frequently utilised to create an emergency corpus - the money that you can get when needed.
Flexibility
Depending on the cash flow requirements, you can invest in liquid funds over a few days, weeks or months. Most fixed deposits lack this type of flexibility without penalty.
Tax-efficient compounding until redemption
The interest is taxed only when your liquid fund is redeemed, unlike the case with fixed deposits, where you are taxed on the interest yearly, and your entire investment is compounded before you sell.
Liquid funds vs savings account vs fixed deposits
It’s helpful to understand how liquid funds compare with other cash-parking instruments:
- Savings accounts offer instant withdrawals but very low interest.
- Fixed deposits can offer higher rates, but your funds are locked in, and interest is taxed yearly.
- Liquid funds offer a middle path: better returns than savings accounts plus liquidity with redemption-based taxation.
Risks associated with liquid funds
Although liquid funds are low risk, they are not risk-free:
Credit risk
If a debt security in the portfolio defaults on payment, the fund’s NAV could drop slightly.
Interest rate risk
Liquid funds are less sensitive to rate changes than other debt funds, but sudden interest rate movements can still affect returns modestly.
Inflation risk
Since returns are moderate, they might not always keep up with inflation over long periods. This can reduce the real purchasing power.
Taxation of liquid funds
If you bought liquid fund units on or after April 1, 2023, it doesn't matter how long you hold them. All gains will be taxed at your individual tax rate. However, if you bought units before this date, then:
- Short-term capital gains: When redeemed in the 2 year period, the gains undergo taxation at your normal income tax slab rate.
- Long-term capital gains: Any gains with a holding period of over 2 years are taxed at a rate of 12.50% without the indexation benefit.
- Dividend income: All the dividends received are taxed according to your slab rate. If the amount is more than Rs. 5000, than 10% TDS is also deducted.
Who should consider investing in liquid funds?
Liquid funds are particularly suitable for:
- Individuals who want to park emergency funds with easy access
- Investors with excess cash for short durations
- Conservative investors seeking low-risk returns
- Those looking to get better returns than a savings account without locking in funds
If your financial goals are long-term wealth creation rather than short-term parking, other equity mutual funds or investment options may be better suited.
Conclusion
A liquid fund is a safe mutual fund which invests in short-term money market and debt instruments to offer capital security, swift access, and superior yields as compared to savings accounts. Liquid funds provide an efficient and convenient solution with professional management and comparatively stable returns when you are creating an emergency fund or simply need a temporary location to store excess cash.
Before investing, always consider your risk tolerance, investment horizon and tax situation.
Frequently asked questions
What is liquid fund used for?
Liquid funds are primarily employed to park short-term excess cash and develop an emergency corpus.
Are liquid funds safe?
They are viewed as low-risk since they invest in short-term instruments that are of high quality but not totally risk-free.
How quickly can I withdraw money from a liquid fund?
Redemption proceeds will normally be credited within one business day of your request.
Do liquid funds pay dividends?
A few liquid funds provide dividend options, yet these are taxable according to your income tax slab.
Is a liquid fund better than a savings account?
Liquid funds generally offer higher returns than savings accounts, but with a slight delay in liquidity.