Difference Between SIP and Mutual Fund




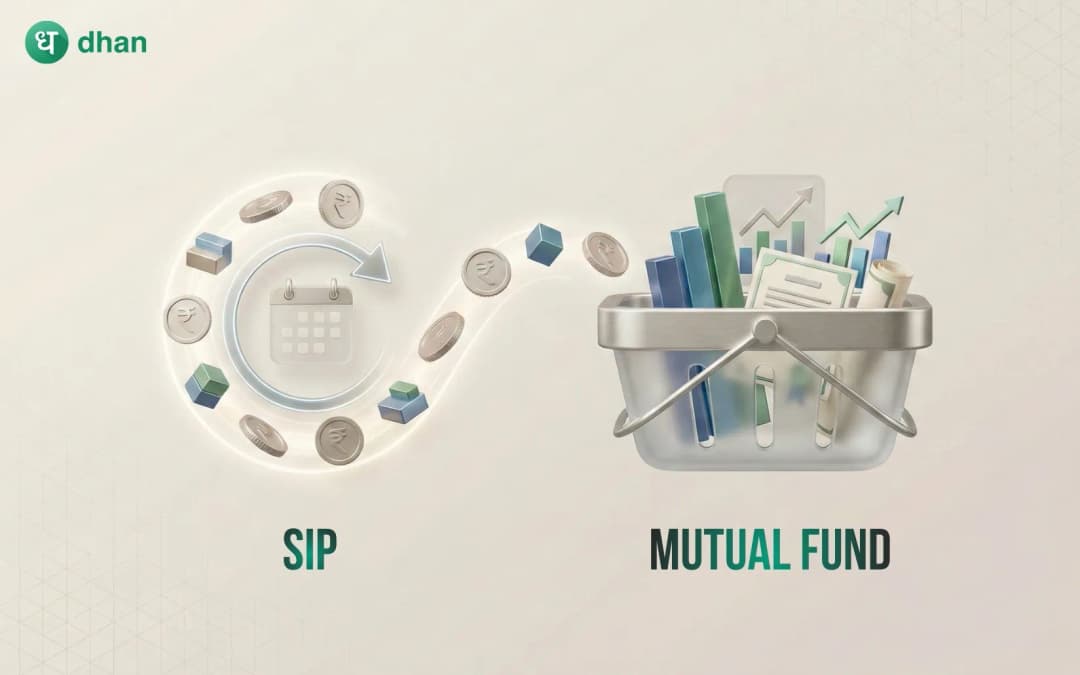


One of the most common misconceptions among new investors in India is the difference between SIP and mutual funds. Many investors think they are two different investment products, when in reality they are working together as an integral part of the same investment ecosystem.
In this blog, we will explore the difference between a systematic investment plan and mutual funds, how they go hand-in-hand, and how to make better investment choices based on an individual's financial goals.
What is a Mutual Fund?
A mutual fund is an investment vehicle that collects funds from different investors to invest in a diversified portfolio of securities such as stocks, bonds, government securities, money market instruments, or a combination of these assets.
When investors invest in a mutual fund, they are buying units of that fund at the prevailing Net Asset Value (NAV). The NAV represents the per-unit market value of all the fund's holdings. As the value of the underlying securities rises or falls, the NAV changes accordingly, which determines the value of the investor's investment.
Mutual funds are of different types and are meant to serve different needs and risk appetites of the investors. Each mutual fund scheme has different investment objectives, risk profiles, and expense ratios. Investors choose funds based on their financial objectives, investment horizon, and risk tolerance.
What is a SIP?
SIP stands for Systematic Investment Plan, which involves making regular (weekly, monthly, quarterly) investments in mutual funds. It is a periodic mode of investing in mutual funds and not an investment product itself. Through SIP, investors can calculate a fixed amount which is to be invested at regular intervals into a mutual fund scheme of their choice using a SIP calculator.
SIPs represent the how or the process of investing, while mutual funds are what or where investors are investing in. SIP is essentially an automated investment discipline where a predetermined amount of funds is transferred from an investor's bank account to their chosen mutual fund on predetermined dates. This fund then results in the buying of mutual fund units at the NAV of that day.
Over time, investors end up with multiple units of mutual funds bought at different NAVs, where more units are bought when prices are low, fewer units when prices are high. This results in a reduction of the average purchasing cost, known as rupee cost averaging.
SIP vs Mutual Fund
Understanding the fundamental differences between SIP and mutual funds is important for investors to make better investment decisions. Some of the differences are:
Common Myths about SIPs and Mutual Funds
Some common misconceptions about SIPs and mutual funds are discussed below to let investors know the difference between SIP and mutual funds:
Misconception 1
SIP returns are better than mutual fund returns. But in reality, SIPs don't generate returns; only the mutual fund does. SIP is simply the method of investing. The returns are purely dependent upon the performance of the mutual fund, and not the method of the investment.
Misconception 2
SIP is a type of mutual fund. But in reality, SIP is an investment facility and not a type of fund. Investors can use SIP to invest in equity funds, debt funds, hybrid funds, or any category of mutual funds.
Misconception 3
Investors can only invest through SIP in mutual funds. But in reality, investors can also invest in the same mutual fund using different methods such as SIP, lump sum, Systematic Transfer Plan (STP), or Systematic Withdrawal Plan (SWP).
Misconception 4
SIP has a lock-in period. But in reality, most SIPs have no lock-in (except ELSS funds, which have a 3-year lock-in). Investors can stop, pause, or redeem their investments whenever they like. Staying in investments long-term provides better results.
Benefits of investing in Mutual Funds through SIP
After understanding that SIP is a way to invest in mutual funds, let's see why this combination works brilliantly for most investors:
Power of compounding
The benefit of starting SIPs early is that it gives the investment more time to compound over decades. For example, when investors invest in a mutual fund for 25 years at 12% yearly returns, the investment amount of Rs 10,000 per month will provide a final corpus of Rs 1.89 crores, despite the investment amount only being Rs 30 lakhs.
Rupee cost averaging
By investing fixed amounts regularly, investors purchase more units when prices are low and fewer units when prices are high. Over time, this can average out the purchase cost and will improve returns from poorly timed lump sum investments.
Financial discipline
SIP inculcates saving and investing discipline. The automatic debit helps make sure that investors prioritise investments before spending, which is the pay yourself first principle that is essential to wealth creation.
Stress-free investing
SIP takes the burden of timing the market, which is even difficult for experts to do with consistent results. With SIPs, investors invest systematically regardless of whether markets are up or down, and this removes emotional decision-making.
Affordability
Starting with small investments makes investing accessible to new investors. Inventors don't have to wait to accumulate large sums of funds to start their wealth creation journey; they can start right away on whatever they can afford.
Conclusion
The difference between SIP and mutual funds is fundamental and also something that is often misunderstood. Mutual funds are investment products with a diversified exposure to markets through professional management. SIP is the systematic way of investing in these mutual funds that brings discipline, affordability, and convenience in the investor's wealth creation journey.
FAQs
Can I invest in mutual funds without SIP?
Yes, SIP is not the only way of investing in mutual funds. You can also invest through a lump sum investment (one-time investment), Systematic Transfer Plan (STP), or manually make multiple investments whenever you have surplus funds. The mutual fund is still the same; the only difference is the method of investment. Many investors use a combination to avail SIPs benefits for regular investments and then add lump sum amounts during market corrections.
What is the minimum amount needed to start a SIP?
Most mutual fund schemes offer you the option to start a SIP with an amount as low as Rs 500 per month, though some fund houses now charge less at Rs 100. However, the minimum amount depends on the fund house and the type of scheme. For meaningful wealth creation, it is important that you start SIP investments early on and increase this amount each year as your income grows through step-up SIPs.
Are SIP returns guaranteed or fixed?
No, SIP returns are not guaranteed or fixed. Since SIP is a way to invest in mutual funds, returns entirely depend upon the performance of the mutual fund scheme underlying it. Equity mutual funds can provide attractive returns over long periods but may also show negative returns in the short term due to volatility in the markets. Debt mutual funds provide more stability with moderate returns. Past performance isn't a guide to future performance.
Is there a lock-in period, or can I stop my SIP anytime?
Most mutual fund SIPs can be stopped, paused, or modified at any time without any penalty or charges. You are given full flexibility. The only exception is ELSS (Equity Linked Savings Scheme) funds, which have a mandatory 3-year lock-in period per investment. However, in ELSS, you also have the option to stop future SIPs, but only the amount that is invested gets locked for three years from the date of each investment. Staying invested for the long term yields better results despite the flexibility to exit.
Which is better for returns: SIP or lump sum investment in mutual funds?
There's no definitive answer as both have advantages based on market conditions. Lump sum investments provide better returns in consistently rising markets because all of your capital is invested from the outset. In contrast, SIPs perform better in volatile or declining markets because of rupee cost averaging. However, as it is extremely difficult to predict the direction of the market, SIP provides a more sensible and stress-free approach for most investors. Experts recommend using SIP for regular investments and investing in lump sums during significant market corrections for better results.